A charge-off is an accounting and regulatory milestone, not a complete account history. For collections leaders, the key questions are what balance remains, who has authority to collect it, what restrictions apply, and how the next action will be recorded.
A charge-off does not automatically cancel an obligation. It also does not prove that a balance remains legally collectible. Bankruptcy, settlement, ownership, limitations periods, contract terms, and other facts can change the available treatment. Confirm the account before placing or working it.
What a charge-off means
A creditor records a loss or removes an amount from its active loan or receivables classification under the applicable accounting and supervisory framework. The treatment depends on the institution, product, regulator, and policy.
For example, the OCC's Uniform Retail Credit Classification and Account Management Policy generally sets charge-off timing of 120 days past due for closed-end retail loans and 180 days for open-end retail credit at institutions covered by that policy. Those figures are not universal deadlines for every lender, product, or account. Credit unions and other institutions may follow different applicable requirements.
What changes after charge-off
The account may move to a specialized internal queue, a servicing partner, or a debt buyer. Each transition creates a control point. Before outreach, teams should confirm:
- Current owner and authority to collect
- Accurate principal, interest, fees, payments, and credits
- Account status, including bankruptcy, settlement, dispute, or deceased status
- Applicable consumer-protection and communication restrictions
- Any prior placement, recall, or return reason
- The approved treatment and channel for the account
A charge-off entry alone does not establish these facts. If the account data is incomplete or conflicts across systems, resolve the discrepancy before collection activity proceeds.
Manage recovery as a controlled portfolio
Post-charge-off recovery works best when account selection, customer communication, payment options, and outcome reporting stay connected. Segment accounts using approved criteria such as balance, age, prior contact, payment history, and current account status. Do not use a score or model as the sole basis for a decision that requires human or legal review.
Track operational measures that explain the result: placement-to-contact rate, right-party contact, payment arrangements offered, promises kept, dollars received, complaints, disputes, and reconciled balances. Separate cash received from amounts merely promised or initiated.
If an account is placed with a third party, define how balances, disputes, payments, and account updates return to the creditor. Reconcile fees and recoveries against account-level records. The creditor should retain visibility into what was collected, what remains, and why the next action is appropriate.
Reduce preventable losses earlier
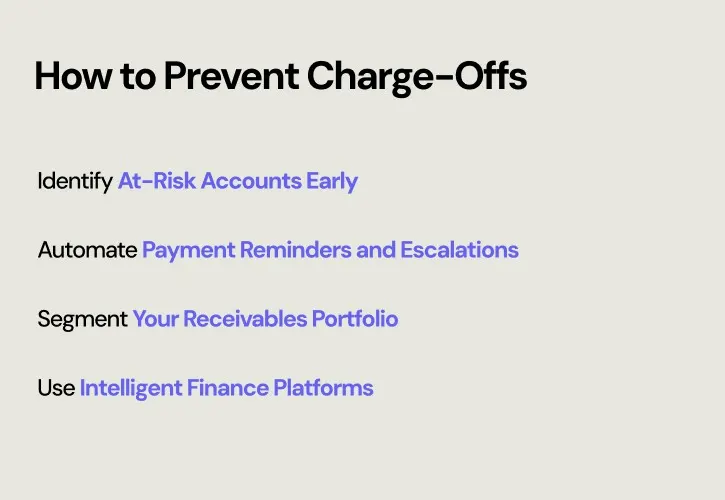
Charge-off strategy should also look upstream. Review roll rates, cure rates, broken promises, and time from missed payment to first meaningful contact. A late reminder may arrive after the customer has already lost the context or ability to resolve the account.
A connected first-party workflow can make the earlier stages easier to manage: identify accounts that need attention, provide clear account information, offer only approved payment options, route sensitive cases for review, and keep outcomes visible to servicing and finance teams.
Keep recovery tied to account history
FinanceOps connects approved outreach, customer responses, payment resolution, and account updates in a traceable workflow. Your team defines the rules and review points.