A charge-off means a creditor has recognized some or all of a debt as a loss in its accounting records under the applicable framework. It does not automatically forgive the debt, close every recovery option, or transfer ownership to a collection agency.
For collections leaders, the next questions are practical: what balance remains, who can collect it, what restrictions apply, and how will payments return to the financial records?
Charge-off versus a closed account, forgiveness, and debt sale
These terms describe different events. One account can have more than one of these statuses, so do not use them interchangeably.
| Term | What it describes | What teams must verify |
|---|---|---|
| Charge-off | Recognition of a loss in accounting records | Remaining obligation, recoverable balance, and approved treatment |
| Closed account | An account no longer available for new use | Whether a balance remains and how it is serviced |
| Debt forgiveness or cancellation | Release of some or all of an obligation | The agreement, discharge, or other basis and its scope |
| Debt sale | Transfer of ownership to a buyer | Effective date, ownership records, and servicing authority |
| Write-off | A broader accounting term often used alongside charge-off | The institution's terminology and ledger treatment |
“Charged off as bad debt” describes the creditor's loss classification. It is not, by itself, evidence that the customer no longer owes anything. Conversely, an accounting entry does not establish that a balance is legally collectible. Settlement, bankruptcy, limitations, contract terms, and other facts can restrict or eliminate recovery options.
When does a charge-off happen?
There is no single delinquency deadline for every creditor or product. The OCC's Uniform Retail Credit Classification and Account Management Policy generally uses 120 days past due for closed-end retail loans and 180 days for open-end retail credit at covered institutions.
The same policy specifies 180 days for covered retail loans secured by one- to four-family residential real estate and addresses bankruptcy, death, and fraud separately. Those details matter when designing a queue or reporting rule.
Confirm the institution, product, applicable framework, and approved accounting policy with finance and compliance. Do not copy the 120/180-day framework onto every commercial invoice, credit-union product, or other receivable.
What changes after charge-off?
A creditor may keep recovery in-house, appoint a servicing or collection provider, sell the debt, or restrict further activity. Placement with a provider does not itself mean ownership has transferred.
Before outreach, verify:
- Current owner and authority to collect.
- Principal, permitted interest and fees, payments, and credits.
- Bankruptcy, settlement, dispute, deceased, and identity-theft status.
- Applicable communication and legal restrictions.
- Prior placements, recalls, and return reasons.
- Approved treatment, channel, and review owner.
If source records conflict, resolve the exception before collection proceeds. Do not use a charge-off code as a substitute for the underlying account history.
A practical post-charge-off recovery workflow
1. Reconcile the placement
Create an opening snapshot showing the account identifier, charge-off date and amount, current claimed balance, subsequent transactions, and owner. Keep the accounting loss amount separate from the amount currently claimed.
For example, an account charged off at $1,000 may later receive a $200 payment. Assuming no other adjustments, a placement file still showing $1,000 would overstate the remaining balance. Reconcile the payment before the next communication.
2. Segment eligible accounts
Use approved criteria such as age, balance, contact history, prior payment behavior, and current restrictions. Route disputed, bankrupt, or uncertain accounts into the appropriate review process. A score must not replace a legal or human decision where one is required.
3. Apply approved outreach and options
Use the current account balance and authorized payment options. Make customer responses visible to the working queue, including hardship requests, disputes, and representation notices. A new restriction should change the next action rather than merely create a note.
4. Record outcomes separately
Distinguish a promise to pay, a scheduled payment, an initiated transaction, and cleared cash. Record failed payments, reversals, and returned funds so that an earlier outcome does not remain incorrectly marked as resolved.
5. Reconcile recoveries and release exceptions
Match payment records, provider reports, fees, and remittances to the account and financial records. Finance should approve the accounting treatment. Keep an exception owner and resolution date for missing or inconsistent transactions.
If an account is recalled or moved to another provider, send the latest balance, history, disputes, and restrictions with it. Confirm that the previous provider's outreach stops as required by the handoff.
Measure recovery with consistent definitions
| Measure | Suggested definition | Why it helps |
|---|---|---|
| Gross recovery rate | Cleared recoveries divided by the defined opening placement balance | Compares cohort outcomes |
| Net recovery | Cleared recoveries less defined reversals and collection costs | Shows retained value |
| Promise-kept rate | Fulfilled promises divided by promises due in the period | Separates commitments from results |
| Reconciliation exceptions | Unmatched or conflicting transactions still open | Exposes balance and reporting gaps |
| Dispute and complaint rates | Cases relative to a defined account or contact population | Adds context to recovery performance |
Define dates, denominators, included costs, and treatment of reversals before comparing portfolios. A young cohort and a long-worked cohort are not directly comparable. Avoid counting a scheduled payment as recovered cash.
Charge-offs and credit reporting are separate decisions
Do not promise that paying a charged-off balance automatically removes its history from a credit report. The CFPB explains that accurate negative information generally cannot be removed simply because it is negative.
Where credit reporting is involved, route corrections and disputes through the applicable furnishing and reporting process. The collections status, accounting status, and reported status should be checked together, but each has its own requirements.
Reduce preventable losses earlier
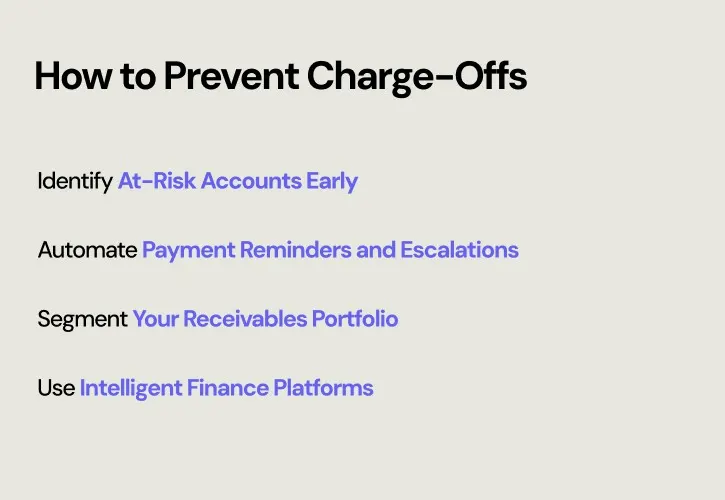
Review roll rates, cure rates, broken promises, and the time from a missed payment to meaningful contact. These measures can reveal where earlier servicing or an approved payment option may help.
Keep the goal specific: resolve eligible balances sooner while respecting account restrictions. Reminders, segmentation, and payment options cannot guarantee that an account avoids charge-off or justify delaying a required accounting action.
Keep recovery tied to account history
FinanceOps connects configured outreach, customer responses, payment resolution, and account updates. Autopilot supports approved routine workflows; Copilot helps collectors review account context when human judgment is needed.
Your team defines the strategy, review points, payment options, and applicable restrictions. Explore FinanceOps Collections and Autopilot, or book a demo.
For a related account-handling process, see our collection dispute-letter guide.