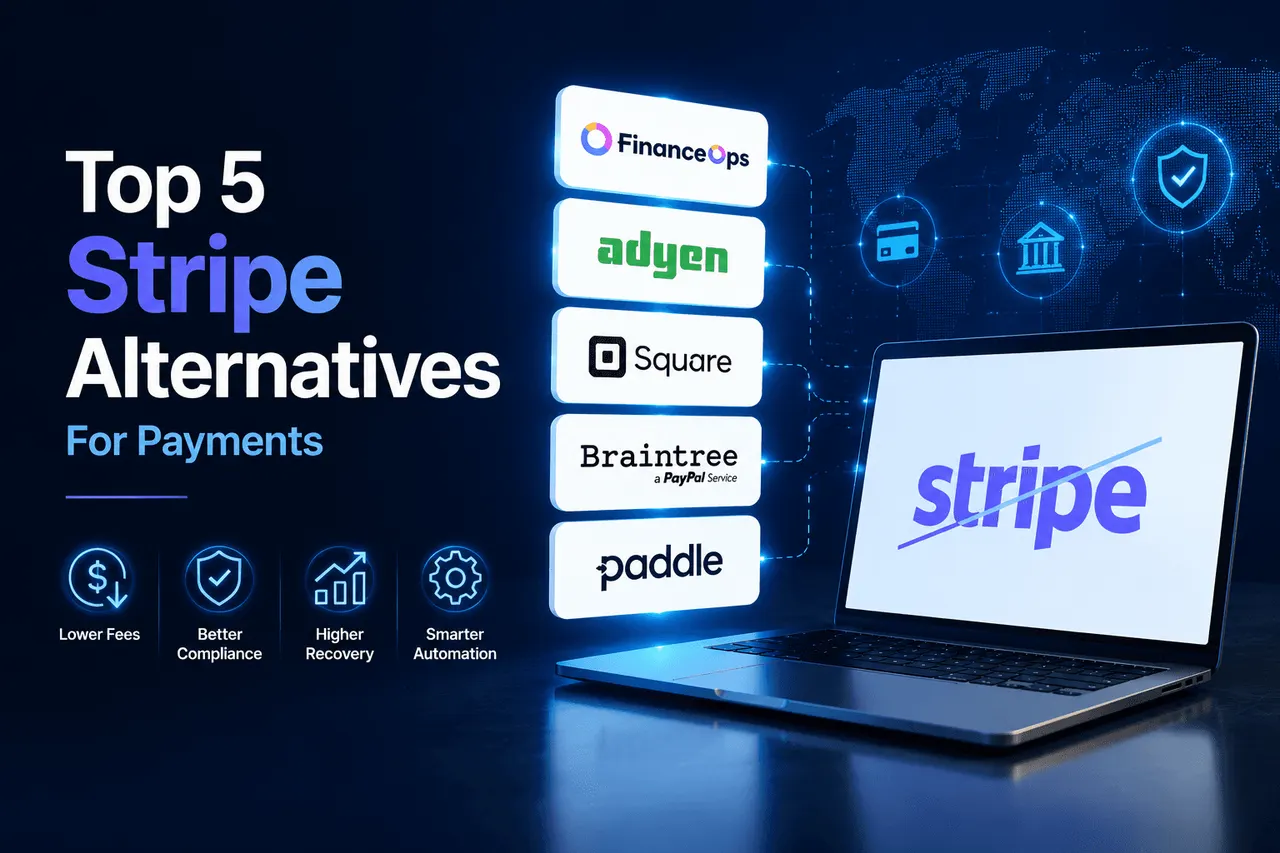
Many buyers searching for Stripe alternatives need a different checkout or payment-processing provider. Others have a different problem: customers have already missed a payment, and collecting it takes too much manual work.
Those are not interchangeable requirements. Stripe, Adyen, Square, Braintree, and Paddle provide payment or merchant-of-record services with different strengths. FinanceOps is primarily a first-party collections and recovery workflow platform, and can work with an organization's existing payment processor. Comparing them requires separating payment acceptance from what happens when payment is overdue.
This guide outlines five options worth evaluating, their intended use cases, and how to evaluate the additional collections capabilities a finance team may need. The order is for explanation, not an evidence-backed ranking.
What should you evaluate before replacing Stripe?
Define the problem before choosing a vendor.
- Payment acceptance: Card and bank payment methods, checkout experience, supported markets, settlement, disputes, refunds, and payment failure handling.
- Billing: Subscriptions, invoicing, taxes, retries, and recurring payments.
- Collections: Delinquency prioritization, approved outreach, customer conversations, payment arrangements, dispute routing, payment-status verification, and reconciliation.
- Risk and governance: Data protection, access control, applicable communication rules, audit records, customer permissions, and controls on automated actions.
- Total cost: Processing fees, software fees, success fees, fixed per-payment charges, optional services, integration work, and the cost of staff effort.
A lower advertised transaction rate does not establish a lower total cost of recovery. Compare the same payment mix, portfolio, and verified recovery outcomes.
Five providers and the use cases they serve
| Provider | Primary fit | What a collections team should check |
|---|---|---|
| Adyen | Enterprise payments across channels and markets | Which payment methods, failure events, and account data can be exposed to your recovery workflow |
| Square | Businesses that want integrated commerce, point-of-sale, and payment acceptance | Whether the existing tools meet your overdue-balance and multi-step servicing requirements |
| Braintree | Payment processing with PayPal ecosystem integrations | Which methods, failure states, webhooks, and settlement details support downstream follow-up |
| Paddle | SaaS sellers seeking a merchant-of-record model for subscriptions and tax administration | Which merchant, billing, collections, and account responsibilities Paddle handles in your contract |
| FinanceOps | Organizations seeking first-party AI-assisted collections, servicing, payment follow-up, and reconciliation | Existing processor compatibility, permitted actions, recovery attribution, total pricing, and measurable outcomes |
This is not an apples-to-apples list of payment gateways. FinanceOps fills a collections workflow need that may exist alongside any suitable processor. Provider capabilities and pricing can change; validate them directly with each vendor.
1. Adyen: Enterprise payment infrastructure
Adyen offers payment capabilities designed for organizations operating across channels and geographies. It is relevant when enterprise payment acceptance, acquiring, and payment operations are the primary need.
Evaluate: market and method coverage, commercial terms, integration requirements, settlement reporting, and whether retry or failed-payment events can be consumed by your receivables systems.
Collections distinction: A processor event can tell you that a payment failed. Resolving an overdue account may require a customer explanation, an authorized alternative arrangement, and updated account records.
2. Square: Payments integrated with commerce
Square is a practical option for organizations prioritizing point-of-sale, online payments, and related business tools.
Evaluate: commerce workflows, supported payment methods, invoicing features, customer communications, and total fees for your particular business model.
Collections distinction: Sending an invoice or retrying a transaction is not identical to managing a high-volume delinquent portfolio with disputes, hardship routing, and account-level treatment policies.
3. Braintree: Payment processing in the PayPal ecosystem
Braintree is relevant to businesses that need payment acceptance and integration with PayPal payment capabilities.
Evaluate: wallet support, supported markets, API and webhook coverage, transaction outcomes, settlement details, and integration costs.
Collections distinction: Payment infrastructure provides transaction information; a separate recovery process may still be needed to interpret customer responses and coordinate permitted next steps.
4. Paddle: SaaS merchant-of-record services
Paddle is especially relevant to digital and software sellers evaluating a merchant-of-record model that addresses billing and certain tax and payment administration responsibilities.
Evaluate: merchant-of-record scope, subscription features, payment methods, billing control, refund and dispute procedures, and contractual economics.
Collections distinction: Merchant-of-record billing responsibilities are not the same as working a creditor's aged receivables portfolio. Verify ownership of the customer relationship and what recovery actions are permitted.
5. FinanceOps: First-party collections and payment recovery
FinanceOps focuses on the work around overdue payments, rather than primarily serving as a general-purpose checkout replacement.
Organizations can use FinanceOps with existing account, servicing, billing, and payment systems subject to integration scope and commercial terms.
How the recovery workflow operates
- FinanceOps Score: Helps prioritize accounts using collectibility, delinquency, engagement, and promise-to-pay context. A score is a prioritization signal, not a guaranteed payment probability.
- Strategy Builder: Applies approved outreach policies, permitted payment arrangements, and escalation boundaries.
- Autopilot: Coordinates eligible routine first-party outreach, conversations, and follow-up.
- Copilot: Supports human collectors with account context and guidance when staff manage a conversation.
- Agentic Payments and reconciliation: Connect payment options and follow-up with transaction outcomes and account records through configured integrations.
- Human review: Escalates disputed balances, hardship requests, or policy exceptions when judgment or verification is needed.
This is particularly relevant when the expensive part of collections is not the transaction itself, but all the work required to move an unpaid account toward a verified outcome.
FinanceOps pricing: 1.5% + $1
For the stated Autopilot success-based offer, FinanceOps charges:
- 1.5% of eligible cash recovered
- $1 flat fee per successful payment
- No percentage success fee on balances without eligible recovery
- No standard setup or subscription fee under this offer
Payment processing, Voice AI, tracing, and other optional services may cost extra. Copilot is priced separately. Eligibility, payment attribution, reversals, and any additional charges should be confirmed in the agreement.
Illustrative example: If $100,000 of eligible cash is recovered through 400 successful payments, the quoted Autopilot fees would be $1,900 ($1,500 percentage fee + $400 fixed fees), excluding processing and optional services. This is a fee calculation, not a forecast of recovered cash or a like-for-like comparison with a payment processor's merchant processing charges.
What customer results can and cannot establish
FinanceOps has published case studies describing outcomes such as reduced collection costs and increased payments for specific deployments. Those are customer-specific outcomes, not a guaranteed or universal uplift. Before treating any result as a benchmark, review the portfolio, baseline, measurement period, attribution rules, and cost definition.
Read FinanceOps customer stories.
Payment processing versus recovery: a practical comparison
| Buyer question | General payment processor | FinanceOps collections workflow |
|---|---|---|
| Can the customer make a payment? | Core purpose | Connects payment options through configured processors and integrations |
| Can the system report transaction failure? | Often through APIs, portals, or webhooks, depending on provider and setup | Can use integrated payment events in follow-up workflows |
| Can it prioritize an overdue portfolio? | Not necessarily a core payment-processing function | FinanceOps Score supports prioritization |
| Can it manage approved outreach and arrangements? | Varies by provider, product, and integrations | Autopilot supports configured first-party workflows |
| Can it route disputes and hardship? | Varies by workflow and service | Configured staff review and escalation |
| Can it confirm an applied payment? | May provide transaction and settlement records | Requires connected authoritative account and payment data |
| Does it replace the existing payment processor? | May replace or supplement an existing processor | Not inherently; it can operate alongside an existing processor |
The practical decision is often not “Stripe or FinanceOps?” It is “Do we need different payment infrastructure, a better recovery workflow, or both?”
How CFOs should build the business case
Start with a comparable eligible portfolio and a clear baseline. Measure:
- Verified and applied recovered cash, net of refunds and returns.
- Percentage success fees, fixed per-payment fees, processor costs, and optional services.
- Internal staff time and cost per dollar recovered.
- Promise-to-pay fulfillment and exception resolution times.
- Complaints, restricted-contact incidents, and customer experience.
- Integration effort, implementation risk, and controls over automated activity.
Where practical, compare a pilot with a comparable control group. More activity, a higher score, or more promises does not by itself establish incremental recovery.
Bottom line
Stripe and other payment-processing platforms solve important payment acceptance and billing needs. FinanceOps addresses a related but different challenge: what happens when the balance is still unpaid and someone needs to coordinate the next permitted action.
For organizations with growing overdue portfolios, improving collection economics may require both sound payment infrastructure and a connected first-party recovery workflow.
Book a FinanceOps demo to review your portfolio, existing processor, permitted treatment strategies, and the 1.5% + $1 Autopilot offer.