By Pragas Nanthakumar, CEO and Co-founder of FinanceOps
In 2026, AI-powered accounts receivable will become a CFO conversation because it changes the economics of recovery. The strategic question is no longer how many reminders a team can send. It is how much cash the institution can recover, at what cost, with what level of control, and without weakening the member relationship.
For credit unions, this is especially important. Thousands of viable accounts can sit below the threshold for sustained manual attention. The balances are real, but the labor required to pursue them makes the work uneconomical.
AI accounts receivable automation changes that calculation. It can expand portfolio coverage, reduce the cost per resolved account, and create operating leverage without turning every increase in delinquency into a hiring decision.
The CFO Metric That Matters
Most collection dashboards emphasize activities: calls placed, emails delivered, accounts assigned, and promises recorded.
CFOs need a different view.
The better question is: What is the net economic return on every dollar recovered?
A useful model is:
Net recovery value = cash recovered minus labor, vendor fees, communication costs, exceptions, and the cost of delay.
This exposes a weakness in traditional collections. A portfolio can show acceptable gross recovery while still producing poor economics because too many employees, systems, and handoffs are required to generate the result.
AI should improve the entire equation. If it merely adds another software fee while leaving the same manual work behind, it has not transformed accounts receivable.
For a deeper explanation of the underlying technology, read Accounts Receivable Automation: 2026 Guide. This article focuses on the CFO decision: whether the operating model produces measurable financial leverage.
Portfolio Coverage Is a Choice
Every credit union makes an implicit capital-allocation decision when it determines which accounts receive attention.
High-balance and high-risk accounts usually move to the front of the queue. Smaller balances, early-stage delinquencies, and accounts previously worked by outside agencies often receive less attention. The decision is understandable because collector time is limited.
However, deprioritization does not remove the receivable from the balance sheet. It only reduces the probability of recovery.
FinanceOps Agentic AI can change portfolio coverage from a staffing constraint into a strategy decision. Credit unions can define which eligible accounts should receive outreach, which actions are permitted, when engagement should stop, and when a person must intervene.
The CFO gains a more valuable question: not “How many accounts can our team work?” but “Which accounts are economically recoverable under an AI-enabled model?”
The 2026 CFO Decision Framework
| CFO question | Traditional approach | FinanceOps Agentic AI approach |
|---|---|---|
| What limits portfolio coverage? | Collector capacity and agency economics | Credit union policy and account eligibility |
| How does cost scale? | Cost rises with staffing and outreach volume | Cost is increasingly tied to resolved outcomes |
| What is the operating unit? | Campaign, queue, or collector | Individual account and next approved action |
| How is performance measured? | Activity and gross recovery | Net recovery, resolution cost, speed, and control |
| What happens to exceptions? | Manual discovery and reassignment | Structured escalation with account context |
| Who controls strategy? | Vendor configuration or internal procedures | Credit union-defined rules, limits, and approvals |
The distinction matters because CFOs should not approve AI based on novelty. They should approve it when the system improves portfolio economics and makes performance more predictable.
Operating Leverage Without Displacement
The best use of AI is not replacing skilled collectors. It is removing low-value repetition from their day.
FinanceOps AI agents can execute approved outreach, maintain conversation context, answer routine questions, present permitted payment options, monitor commitments, and route exceptions. Collectors can focus on disputes, hardship cases, complex negotiations, complaints, and situations where judgment matters.
This creates operating leverage. The credit union can manage a larger eligible portfolio without increasing headcount at the same rate.
The role of the collector also becomes more strategic. Experienced employees help define strategies, supervise AI behavior, review outcomes, and refine escalation rules. Their knowledge becomes reusable operating logic instead of remaining trapped inside individual queues.
How FinanceOps Agentic AI Works
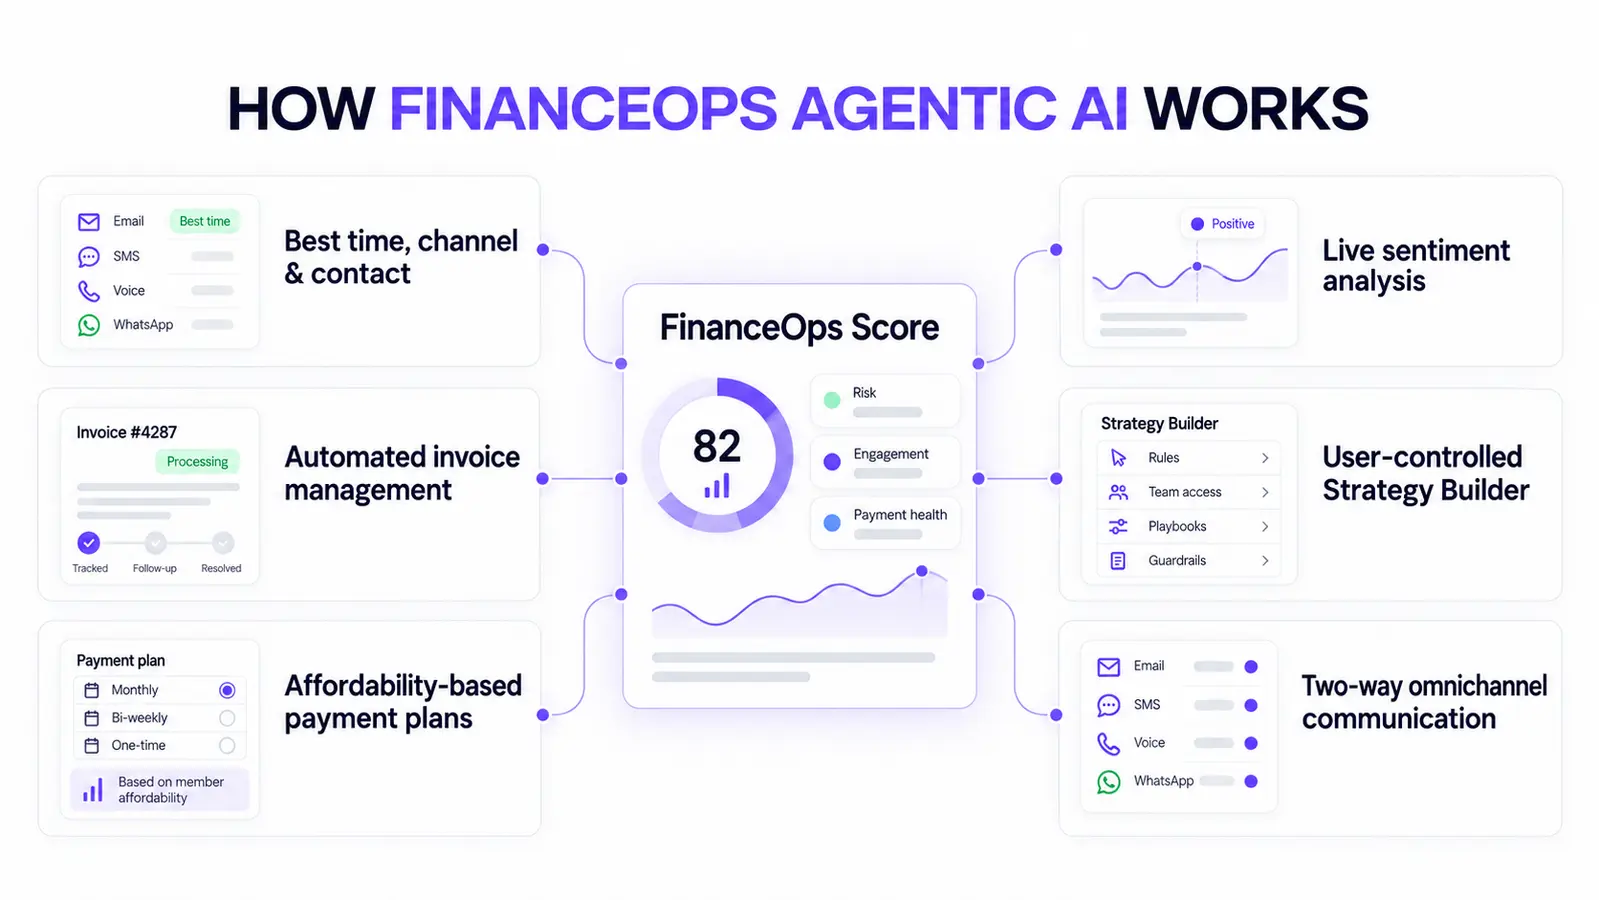
FinanceOps Agentic AI connects seven capabilities inside one governed servicing and collections workflow:
- FinanceOps Score: Continuously prioritizes accounts using collectibility, delinquency, engagement, and payment-commitment signals. It gives every other capability a current account-level decision signal.
- Best Time, Best Channel, and Best Contact: Determines when, where, and whom to contact based on response likelihood, permissions, and available account context.
- Live Sentiment Analysis: Detects engagement, confusion, frustration, and potential hardship signals so the workflow can adjust tone or escalate.
- Two-Way Omnichannel Communication: Maintains relevant context across SMS, email, voice, webchat, and self-service interactions rather than treating each channel as a separate campaign.
- User-Controlled Strategy Builder: Converts credit union policies, segmentation, communication limits, payment boundaries, and escalation rules into executable controls.
- Affordability-Based Payment Plans: Presents only institution-approved options designed around the member's ability to sustain the commitment.
- Automated Invoice Management: Connects outreach with invoice status, payment activity, retries, disputes, reconciliation, and the system of record.
These capabilities are designed to work together. FinanceOps Score informs prioritization. Contact intelligence selects the next permitted interaction. Sentiment and member responses update the workflow. Strategy Builder controls what the AI may do. Payments and invoice management verify whether the account actually reached resolution.
The value is not seven disconnected features. It is a closed operating loop where every new account signal can change the next approved action.
Explore how FinanceOps Autopilot executes approved servicing and collections strategies.
Build the CFO Scorecard
A FinanceOps Agentic AI program should be evaluated through financial and operational outcomes. CFOs should establish a baseline before deployment and monitor a concise scorecard:
- Eligible portfolio coverage: The percentage of accounts receiving an appropriate action.
- Net recovery value: Cash recovered after direct operating and vendor costs.
- Cost per resolved account: The total cost required to reach a completed outcome.
- Cash-conversion velocity: The time between account eligibility and payment or resolution.
- Kept-promise rate: The percentage of payment commitments completed as agreed.
- Human-intervention rate: The share of accounts requiring manual work.
- Exception quality: Whether disputes, hardship, and sensitive cases reach the correct team with complete context.
- Member-risk indicators: Complaints, opt-outs, repeated contact, and negative experience signals.
Cash-conversion velocity also shows whether AI DSO reduction is occurring in practice. AI accounts receivable automation should shorten time to resolution without increasing unnecessary member contact.
This scorecard prevents a common mistake: declaring success because communication volume increased. More activity is not the objective. More economically efficient resolutions are.
Readers looking specifically for DSO mechanics can see How AI Reduces DSO Without Raising Collection Costs. The CFO scorecard should translate those mechanics into investment accountability.
Governance Is an Internal Control
For a CFO, AI governance belongs beside financial controls, vendor oversight, and operational risk.
The credit union should be able to define eligible actions, communication rules, payment-plan limits, approval requirements, and stop conditions. Teams should be able to test strategies before launch, review why an action occurred, and reproduce the account history during an audit or complaint review.
Governed autonomy means the AI can act independently only inside boundaries established by the institution.
That is materially different from giving a general-purpose model access to member accounts and asking it to “optimize collections.” The credit union must own the policy. The platform must make that policy executable, inspectable, and enforceable.
For debt collectors covered by the FDCPA, the CFPB Regulation F rule addresses debt-collection communications and prohibited practices. Applicability depends on the institution, account, role, jurisdiction, and channel, so legal and compliance teams should approve the deployed strategy.
See how FinanceOps Strategy Builder turns approved policies into executable workflows.
Credit Union Proof Point
A business case becomes credible when the economics work on accounts that traditional models have already deprioritized.
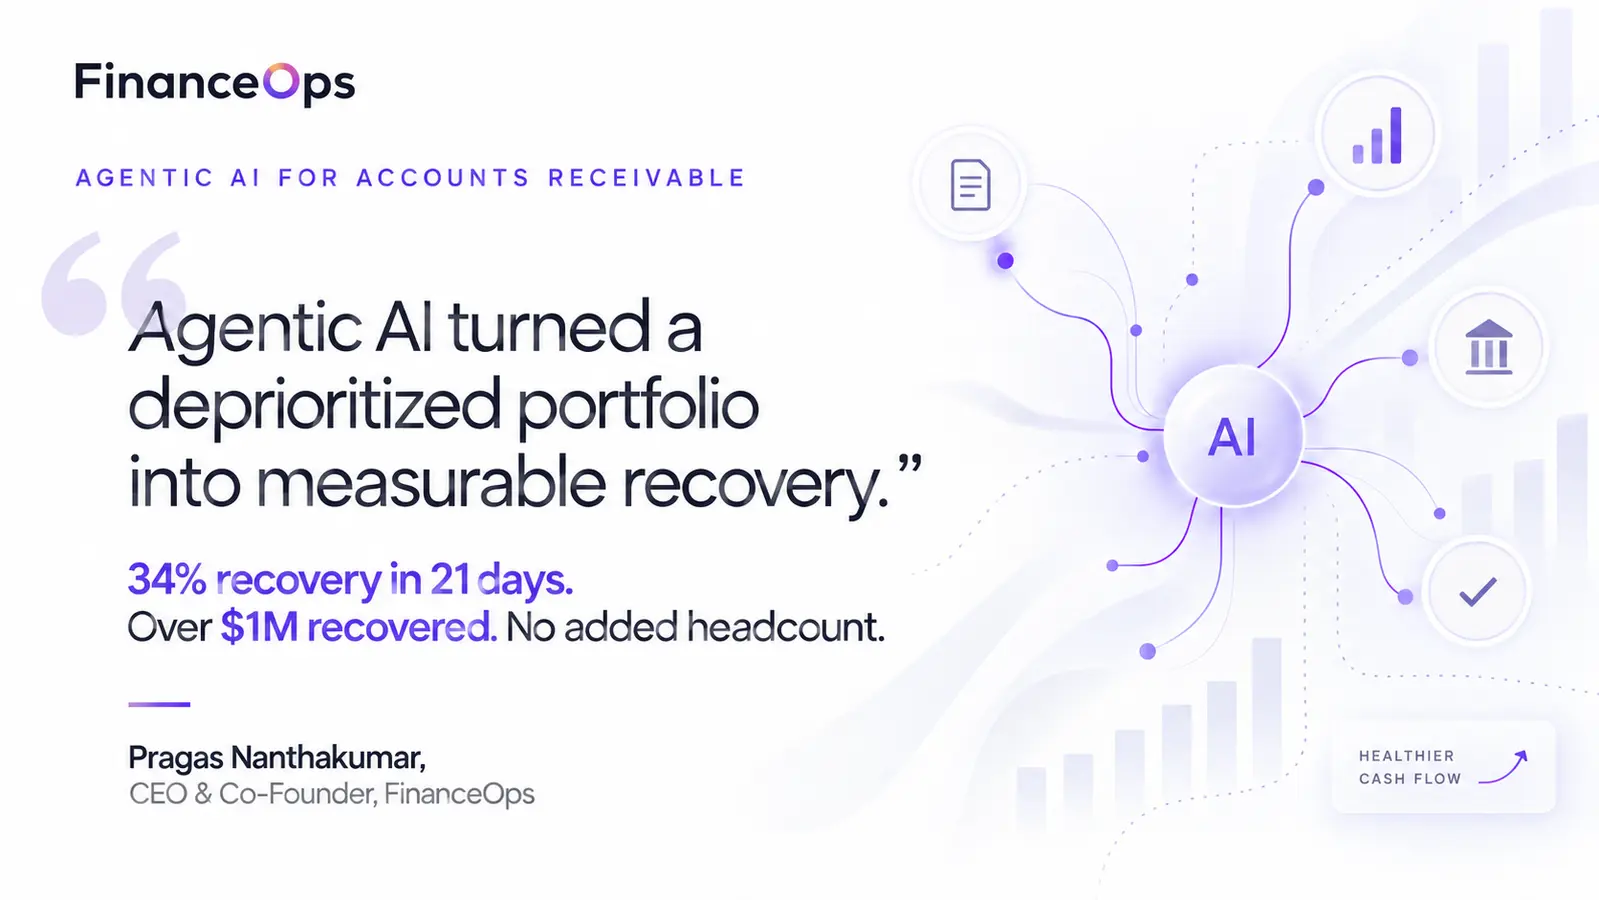
At LA Federal Credit Union, a segment of late-stage accounts had been completely given up on by legacy agencies. Within 21 days, the portfolio achieved a 34% recovery rate and recovered more than $1 million without adding a single employee.
The strategic lesson is not simply that AI can increase recovery. It is that AI can make a previously uneconomical portfolio worth working.
That is the category of result CFOs should demand: incremental cash, measurable speed, and no proportional increase in operating capacity.
Pricing Reveals Incentives
The commercial model is part of the technology decision.
A platform can promise efficiency while charging implementation fees, platform fees, communication fees, user licenses, and per-member charges before producing an outcome. That structure transfers adoption risk to the credit union.
FinanceOps offers qualifying credit unions an outcome-based model with no upfront cost, platform fee, or separate SMS, email, call, or per-member fee. FinanceOps earns 1.5% of the amount successfully collected and is paid only when the credit union recovers cash.
For CFOs, this creates a clearer economic test. The vendor's revenue depends on the credit union's recovery.
Five Questions Before Approval
Before approving a FinanceOps Agentic AI initiative, I would ask:
- What new cash will this produce? Separate incremental recovery from balances the existing team would have collected anyway.
- Which operating costs will change? Measure labor, vendor, communication, exception, and reconciliation costs.
- How much of the portfolio becomes economically serviceable? Pay particular attention to small-balance and previously deprioritized segments.
- What actions remain under credit union control? Confirm limits, approvals, auditability, and human escalation.
- How will we know when to expand? Define the performance and risk thresholds required before adding accounts, channels, or autonomous actions.
Start with a bounded portfolio. Establish the baseline. Run the strategy inside approved controls. Expand only when the evidence supports expansion.
My 2026 Prediction
I recently shared this vision with the National Credit Union Collections Alliance.
My prediction is that FinanceOps Agentic AI for accounts receivable will move from an innovation discussion to a capital-allocation discussion in 2026. CFOs will evaluate AI based on the cash it unlocks, the operating capacity it creates, and the accountability built into the model.
The winning systems will not be the ones that generate the most messages. They will be the ones that turn more eligible receivables into governed, measurable, and economically efficient resolutions.
Watch the full NCUCA presentation.
See how FinanceOps Agentic AI supports credit union servicing and collections.