A customer says, "I can pay $400 today if you waive the rest." An AI agent can reply in seconds. But speed is not the question a CFO or compliance director should ask.
Who authorized the discount? Is the account eligible? What if the balance is disputed? And what evidence would an auditor see tomorrow?
This is the difference between autonomous activity and governed collections automation. A useful AI agent must execute the organization's approved strategy, not invent its own limits as a conversation unfolds.
Quick answer: AI collections strategy automation uses configurable rules for account segmentation, tone, contact cadence, payment arrangements, negotiation authority, restrictions, and human escalation. FinanceOps Strategy Builder provides the policy layer for eligible Agentic AI workflows, while Autopilot executes permitted activity and Copilot supports employee-led exceptions. Appropriate governance also requires current account data, monitoring, testing, and human accountability.
This guide is for CFOs, COOs, Heads of Collections, and Compliance Directors evaluating autonomous collections at scale.
Why a powerful AI collector still needs a rulebook
A scripted dialer usually follows a predefined sequence. A conversational agent can respond dynamically to a customer's question, payment proposal, or frustration. That flexibility can improve service, but it creates a new operational question: which decisions may be made automatically, and which must be approved by the business?
A model's confidence or friendly tone does not authorize a settlement, a debit retry, an additional contact, or the use of protected account information.
The NIST AI Risk Management Framework organizes AI risk management around Govern, Map, Measure, and Manage. It is voluntary guidance, not a government certification of any vendor. Its practical lesson for collections is that organizations must define roles, assess use-case risks, monitor outcomes, and respond to problems.
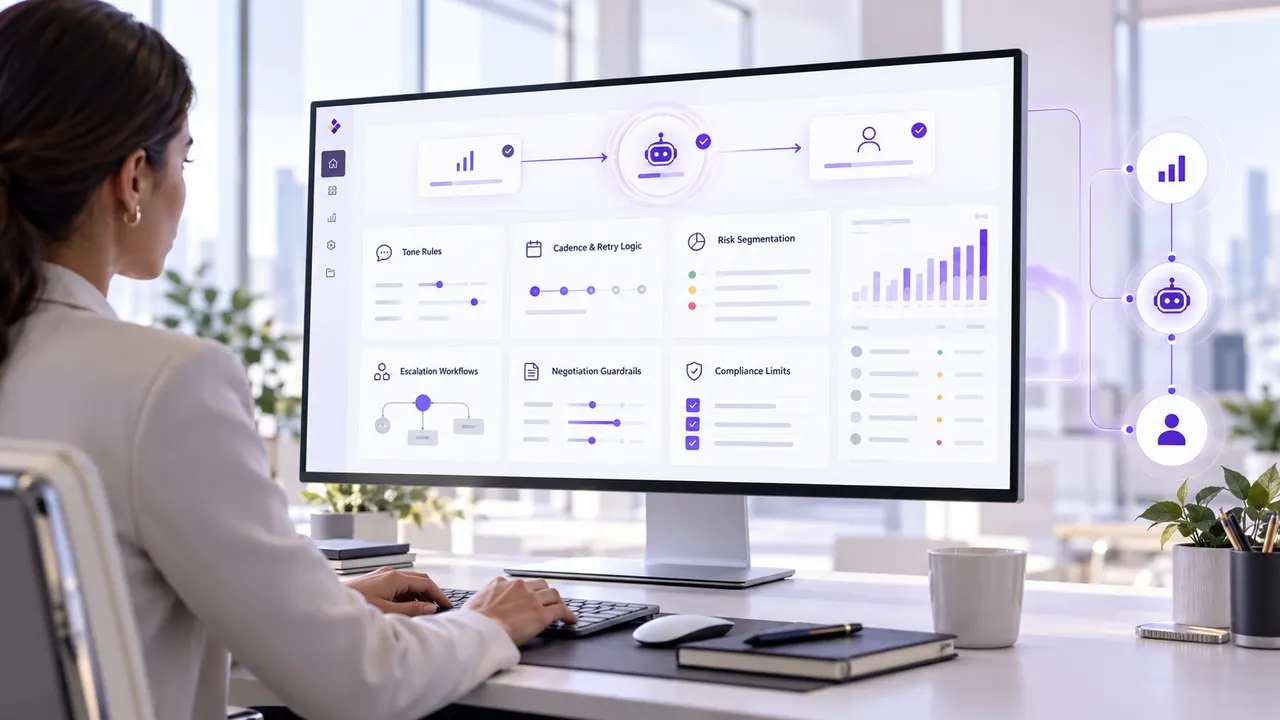
Seven decisions the business must control
| Decision area | What Strategy Builder should govern | Example boundary |
|---|---|---|
| Tone and communication | Approved empathetic, neutral, or firmer language by situation | A hardship disclosure routes to support, not pressure |
| Cadence and retries | Contact frequency, channel, quiet hours, and permitted retry conditions | Stop a scheduled reminder after verified payment |
| Risk segmentation | Eligible account groups and approved treatments | Scoring does not override a dispute hold |
| Escalation | Which cases pass from AI to staff | Suspected fraud, bankruptcy, or unusual request goes to review |
| Negotiation | Permitted arrangement, discount, and settlement limits | No waiver beyond delegated authority |
| Compliance constraints | Channel permissions, legal holds, jurisdiction and account restrictions | Suppress impermissible outreach |
| Evidence and oversight | Decision logs, approval owners, and exception review | Record versioned policy and resulting action |
These are configuration and verification requirements, not a claim that every capability is automatically enabled in every FinanceOps deployment. The business must validate its deployed integrations, permission matrix, and exception handling.
Scenario 1: The customer offers a partial settlement
A borrower offers $400 against a valid $1,000 balance.
A purely conversational system might treat the offer as progress and accept it. A governed workflow should instead check the account type, applicable policy, authority level, settlement eligibility, current balance, active disputes, and any required disclosures.
If the offer fits an approved arrangement, the AI may present the permitted option. Otherwise it should route the proposal to an authorized employee.
The key distinction: AI can conduct the conversation without having unlimited authority to change contractual or legal obligations.
Scenario 2: A customer says the balance is wrong
The member writes, "I paid this already. Stop asking."
That statement could indicate a posting delay, dispute, or contact objection. The agent should not infer the definitive legal status from sentiment alone. It should record the statement, verify the authoritative ledger, apply relevant contact rules and holds, and route the issue for review where required.
Repeatedly sending payment links would turn a solvable servicing issue into an unnecessary collections interaction.
For the difference between account prioritization and verified next actions, read FinanceOps Score Explained.
Scenario 3: The customer requests a payment plan
An eligible customer asks to pay $75 on each payday.
The workflow should validate the actual balance, permitted installments, due-date flexibility, customer agreement, method authorization, and follow-up schedule. Approval is not cash received. Later payment events must be reconciled, including returns and reversals.
For a related operating challenge, see Why Utility Payment Arrangements Fail After Approval.
What compliance guardrails really mean
A product cannot guarantee legal compliance merely by offering a compliance setting. Applicability varies by creditor role, account type, channel, jurisdiction, and facts.
FDCPA and Regulation F
CFPB Regulation F implements the Fair Debt Collection Practices Act for covered debt collectors. A creditor collecting its own debt is not automatically subject to the same requirements as a third-party debt collector, though other requirements and exceptions may apply. Counsel must determine which rules govern each program.
TCPA, calling, and messaging
The FCC's TCPA guidance and applicable rules constrain certain calling and messaging practices. Consent, revocation, call type, and other restrictions should be evaluated for the actual use case. Technology must be configured according to legal review, not a universal assumption that all reminders are permitted.
Data accuracy and privacy
Contact suppression, account access, authorized use of personal information, identity checks, and dispute handling are operational controls. A score or conversational classification should never override an authoritative account hold.
From Strategy Builder to Autopilot, Copilot, and recorded outcomes
The product architecture should follow a sequence that a collections leader can explain:
- Account data: Retrieve current balances, payment events, commitments, and applicable restrictions.
- FinanceOps Score: Prioritize eligible work using delinquency, collectibility, engagement, and promise-to-pay signals.
- Strategy Builder: Apply the organization's approved treatments, channel rules, negotiation limits, and escalation conditions.
- Autopilot: Execute permitted routine first-party engagement and payment follow-up.
- Copilot: Support employees when the action requires human judgment.
- Dashboards: Review verified collection outcomes, costs, complaints, and exceptions.
Explore the Strategy Builder product for the policy design layer. For a broader comparison of agentic and rules-based systems, see Agentic AI Collections Software vs. Traditional Platforms.
A practical policy specification for collection AI
For each treatment, specify the trigger, account segment, data source, permitted channels, tone, maximum arrangement or discount, restrictions, approval owner, exception path, and audit record.
| Trigger | Required check | Approved outcome | Escalation condition |
|---|---|---|---|
| Missed installment | Current balance, payment posting and consent | Permitted reminder or payment option | Unmatched payment or hardship |
| Settlement request | Delegated limit and account eligibility | Authorized offer only | Proposal outside limits |
| Dispute or stop-contact statement | Context and applicable legal rules | Hold, acknowledgement, or review | Ambiguous or sensitive request |
| Failed payment | Return reason and authorization | Permitted next payment step | Authorization or posting uncertainty |
A policy should be versioned, tested in staging with synthetic accounts, and reviewed when rules or integrations change. A deployment that cannot demonstrate what it does on a disputed or protected account is not ready for unattended operation.
How CFOs can evaluate governance and recovery together
| KPI | Why it matters |
|---|---|
| Net applied cash | Cash actually received, correctly applied, and not reversed |
| Cost per dollar recovered | Full collections efficiency, not just messages sent |
| Kept payment arrangements | Whether authorized commitments become verified cash |
| Policy override or violation events | Whether controls are applied and exceptions detected |
| Human escalation completion | Whether complex accounts reach responsible staff |
| Wrong-contact and complaint rate | Whether outreach creates avoidable friction |
| Decision trace completeness | Whether action, rule, account data, and owner can be reconstructed |
A high automation rate is not evidence of a successful program. Evaluate permitted resolutions against a comparable baseline, and review financial performance alongside customer treatment.
Five demonstrations to demand from vendors
Ask the vendor to show:
- A settlement request above the approved discount limit.
- A customer disputing a balance while an automated reminder is queued.
- A payment posting after outreach is scheduled but before delivery.
- A hardship case requiring an employee rather than an AI negotiation.
- A policy rule change and a trace of which version governed the next action.
For procurement questions, consult Enterprise AI Collections: An Evidence Checklist. For financial measurement, read AI Collections ROI: Measure Cash, Cost, and Customer Impact.
The bigger picture: Governance is what makes autonomy usable
Organizations do not need to choose between AI speed and business accountability. They need an architecture that makes autonomy conditional on approved strategy.
FinanceOps Strategy Builder is the policy layer for that operating model. It helps turn written collections SOPs into configured treatments, with Autopilot handling eligible activity and employees remaining responsible for exceptions requiring judgment.
Your AI collector can negotiate. Your organization decides what it is authorized to offer.